How Do Lenders Qualify Mortgage Borrowers?
How Do Lenders Qualify Mortgage Borrowers?
Getting approved for a mortgage involves more than showing a lender that you have enough money for a down payment. Mortgage lenders evaluate several aspects of a borrower’s financial situation to determine whether the borrower is likely to repay the loan as agreed.
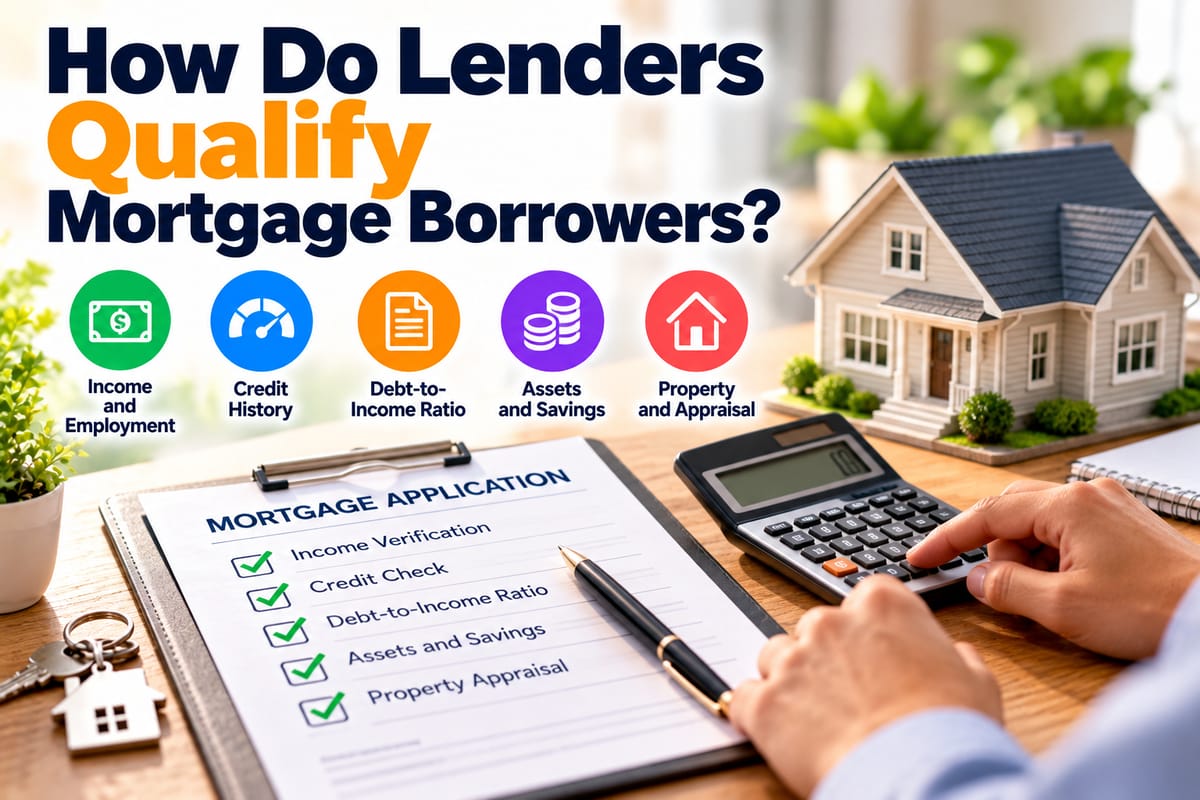
The qualification process typically considers income, employment, existing debts, credit history, assets, down payment, and the property being purchased. Lenders also consider the size and structure of the requested mortgage in relation to the borrower’s finances.
Understanding how lenders qualify mortgage borrowers can help prospective homebuyers prepare their finances, gather the right documents, and develop more realistic expectations before applying for a home loan.
What Does Mortgage Qualification Mean?
Mortgage qualification is the process a lender uses to evaluate whether a borrower meets its requirements for a home loan.
The lender generally wants to answer several questions:
- Can the borrower afford the proposed monthly payments?
- Does the borrower have sufficient and reliable income?
- How much existing debt does the borrower have?
- Has the borrower demonstrated a history of managing credit responsibly?
- Does the borrower have enough money for the required upfront costs?
- Is the property suitable collateral for the loan?
- Does the overall application meet the lender’s requirements?
Qualification criteria vary between lenders and mortgage programs, so there is no single set of requirements that applies to every borrower.
Income Is a Major Part of the Evaluation
Lenders need evidence that a borrower has sufficient income to make mortgage payments.
Depending on the borrower’s circumstances, income can come from:
- Salary or wages
- Self-employment
- Business income
- Investment income
- Rental income
- Bonuses or commissions
- Other qualifying sources
The lender may evaluate not only the amount of income but also its stability and consistency.
A borrower with a high income that varies substantially from month to month may be evaluated differently from someone with a predictable salary.
Employment History Can Matter
Employment history can help lenders assess income stability.
A lender may review:
- Current employer
- Length of employment
- Previous employment
- Occupation
- Income history
- Changes in employment
- Gaps in employment
Self-employed borrowers may face additional documentation requirements because their income can be more complex to verify.
The specific evidence required depends on the lender and the borrower’s employment structure.
Debt-to-Income Ratio
One of the important concepts in mortgage qualification is the relationship between income and existing debt obligations.
A debt-to-income ratio, commonly called DTI, compares certain recurring debt payments with gross income.
A simplified calculation is:
DTI = Monthly debt payments ÷ Gross monthly income × 100
For example, suppose a borrower has:
- Gross monthly income: $6,000
- Existing monthly debt payments: $1,500
- Proposed housing payment: $1,500
Total monthly debt obligations would be $3,000.
The resulting DTI would be:
$3,000 ÷ $6,000 × 100 = 50%
Lenders use debt-to-income measures to help assess whether a proposed mortgage payment is manageable alongside the borrower’s other obligations.
The exact ratios lenders accept vary by loan type, lender, and borrower circumstances.
What Counts as Debt?
Depending on the lender and qualification method, debt obligations can include:
- Car loans
- Student loans
- Credit card payments
- Personal loans
- Existing mortgages
- Other recurring debt obligations
Not every financial expense is necessarily treated as debt for DTI purposes.
For example, ordinary household expenses such as groceries and utilities are important to a household budget but are generally evaluated differently from formal debt obligations.
Credit History Provides a Record of Borrowing
Credit history can provide lenders with information about how a borrower has managed credit in the past.
Lenders may examine:
- Payment history
- Outstanding balances
- Credit utilization
- Length of credit history
- Types of credit accounts
- Recent applications
- Delinquencies or defaults
A strong credit history can demonstrate a consistent record of meeting financial obligations, while negative information may require additional review.
Credit requirements vary considerably between mortgage programs and lenders.
Credit Scores Are Only One Part of the Application
A credit score can be an important part of mortgage qualification, but lenders generally consider the broader financial picture.
Two borrowers with similar credit scores can have different applications because of differences in:
- Income
- Debt
- Savings
- Employment
- Down payment
- Loan amount
- Property characteristics
This is why improving one aspect of an application does not necessarily guarantee approval.
The Down Payment
The down payment is the amount a buyer contributes toward the purchase price from their own funds or other permitted sources.
For example, if a home costs $300,000 and the buyer provides $60,000 toward the purchase, the remaining amount to finance would be $240,000 before considering other transaction costs.
A larger down payment can reduce the amount that needs to be borrowed.
However, the appropriate down payment depends on the mortgage program, buyer’s finances, and other transaction requirements.
Loan-to-Value Ratio
Lenders may also consider the relationship between the mortgage amount and the property’s value or purchase price.
This is commonly expressed as a loan-to-value ratio, or LTV.
A simplified calculation is:
LTV = Mortgage amount ÷ Property value × 100
For example, if a property is valued at $400,000 and the mortgage is $320,000:
$320,000 ÷ $400,000 × 100 = 80% LTV
The LTV can influence lending requirements, pricing, insurance requirements, and other aspects of a mortgage depending on the loan program.
Assets and Savings
Lenders may review a borrower’s available assets to determine whether they have sufficient funds for the transaction and financial reserves.
Assets can include:
- Bank accounts
- Savings
- Investments
- Retirement accounts where permitted
- Other qualifying assets
Lenders may also want to understand the source of funds being used for the down payment and closing costs.
Large recent deposits may require additional documentation to establish where the money came from.
Cash Reserves Can Matter
Some borrowers may need to demonstrate that they have money remaining after closing.
These reserves can provide a financial cushion if unexpected expenses occur after the purchase.
The amount of reserves required depends on factors such as the mortgage program, property type, borrower circumstances, and lender requirements.
Having emergency savings can also help a homeowner handle repairs, maintenance, insurance costs, and other unexpected expenses.
The Property Is Part of the Qualification Process
Mortgage approval is not based entirely on the borrower.
The property itself also matters because it generally serves as collateral for the mortgage.
A lender may evaluate:
- Property value
- Property condition
- Location
- Type of property
- Intended use
- Marketability
- Legal or title issues
The lender wants reasonable assurance that the property provides adequate security for the loan.
The Appraisal
An appraisal can help establish an independent estimate of a property’s market value.
For example, suppose a buyer agrees to purchase a property for $400,000, but an appraisal determines a value of $380,000.
The difference can create complications because the lender may base its lending decision on the lower supported value rather than simply accepting the agreed purchase price.
The exact treatment depends on the mortgage program and lender.
Property Condition Can Affect Financing
A property’s physical condition can also matter.
Serious problems involving areas such as:
- Roofing
- Foundation
- Electrical systems
- Plumbing
- Structural components
- Water damage
- Safety hazards
may require attention before a lender is comfortable proceeding with certain types of financing.
The lender’s appraisal and the buyer’s inspection serve different purposes, so buyers should understand the distinction.
Home Inspections and Mortgage Qualification
A home inspection generally provides the buyer with information about the condition of the property.
The Home Inspection Guide explains the major areas buyers should consider when evaluating a home.
An inspection can uncover issues that affect the buyer’s decision even when those issues do not automatically prevent mortgage approval.
For example, a buyer might discover that a property requires significant roof repairs. That information could affect negotiations, budgeting, or the buyer’s decision to proceed.
Property Due Diligence
Mortgage qualification is only one part of evaluating a home purchase.
Buyers should also investigate matters such as:
- Property ownership
- Title information
- Liens
- Easements
- Zoning
- Permits
- Property boundaries
- Local restrictions
- Outstanding obligations
The Complete Guide to Property Due Diligence provides a broader framework for researching a property before completing a purchase.
How Much House Can You Afford?
Mortgage qualification and affordability are not necessarily the same thing.
A lender may determine that a borrower qualifies for a particular loan amount, but that does not automatically mean the borrower should spend the maximum amount available.
Homeownership involves expenses beyond the mortgage payment, including:
- Property taxes where applicable
- Insurance
- Utilities
- Maintenance
- Repairs
- Homeowners association or similar fees where applicable
- Furnishings
- Emergency expenses
The How to Determine How Much House You Can Afford guide provides additional information about evaluating affordability beyond the basic mortgage qualification process.
First-Time Buyers May Need Additional Preparation
First-time homebuyers often have questions about nearly every stage of the process.
They may need to understand:
- How mortgage applications work
- What documents lenders request
- How much money to save
- How inspections work
- What closing costs involve
- How loan payments are calculated
- What happens after an offer is accepted
The First-Time Home Buyers Guide provides a broader overview of the homebuying process.
Documents Lenders May Request
Mortgage applications typically involve substantial documentation.
Depending on the borrower’s situation, lenders may request:
- Identification
- Proof of income
- Employment information
- Bank statements
- Investment statements
- Tax documents
- Existing debt information
- Information about the property
- Documentation for the source of down-payment funds
Self-employed borrowers may need additional business and income records.
The purpose of this documentation is to allow the lender to verify the information used in the underwriting process.
Why Lenders Verify Bank Statements
Bank statements can help lenders verify available assets and understand the source of funds.
They may look for:
- Required savings
- Down-payment funds
- Closing-cost funds
- Financial reserves
- Large unexplained deposits
- Existing financial obligations
Borrowers should be prepared to explain unusual transactions when requested.
Prequalification vs. Preapproval
The terms prequalification and preapproval are sometimes used differently by different lenders.
In general, prequalification can involve an initial estimate based on information provided by the borrower.
Preapproval typically involves a more detailed review of financial information and documentation.
Neither necessarily guarantees final mortgage approval.
The final loan decision can depend on additional underwriting, property information, appraisal results, documentation, and other conditions.
What Is Mortgage Underwriting?
Underwriting is the detailed process through which the lender evaluates the mortgage application.
The underwriter may review:
- Income
- Employment
- Credit
- Debt
- Assets
- Down payment
- Property
- Loan structure
- Supporting documentation
The purpose is to determine whether the application meets the lender’s applicable requirements.
Why Lenders Ask Questions About Financial Changes
Major financial changes during the mortgage process can affect an application.
Examples include:
- Changing jobs
- Taking on new debt
- Opening new credit accounts
- Making large purchases
- Moving money between accounts
- Receiving unusual deposits
- Changing the planned down payment
Borrowers should communicate significant changes to their lender rather than assuming that an application will remain unaffected.
New Debt Can Affect Qualification
Taking on new debt during the mortgage process can change the borrower’s debt-to-income ratio.
For example, financing a new vehicle could add another monthly payment.
That additional obligation could affect the lender’s assessment of affordability.
For this reason, borrowers should generally avoid making major financial changes during the mortgage process without understanding how they could affect the application.
Closing Costs Matter Too
The amount needed to purchase a home can be significantly greater than the down payment alone.
Depending on the transaction and location, buyers may encounter costs related to:
- Loan origination
- Appraisal
- Inspection
- Legal services
- Title services
- Taxes
- Insurance
- Registration
- Prepaid expenses
- Other transaction costs
Borrowers should understand these costs before committing to a purchase.
Why Stable Financial Management Helps
Mortgage qualification is easier to understand when viewed as an overall assessment of financial capacity.
A lender is generally looking for evidence that the borrower has:
- Reliable income
- Manageable debt
- Appropriate credit history
- Sufficient funds
- A suitable property
- A mortgage structure that fits applicable requirements
No single factor necessarily determines the outcome of every application.
What Can Make Qualification More Difficult?
Several circumstances can create additional challenges.
These may include:
- High levels of existing debt
- Unstable or difficult-to-document income
- Recent credit problems
- Insufficient funds
- Significant unexplained financial transactions
- Property valuation concerns
- Property condition issues
- Incomplete documentation
A challenge does not necessarily mean that financing is impossible. It may simply result in additional documentation, a different loan structure, or the need to address a particular issue.
Preparing Before Applying
Prospective borrowers can make the process more organized by preparing ahead of time.
Useful steps include:
- Review your credit reports and financial records.
- Calculate your recurring debt payments.
- Determine your available savings.
- Estimate a comfortable housing budget.
- Gather income documentation.
- Avoid unnecessary new debt.
- Research appropriate mortgage options.
- Understand likely upfront costs.
- Organize property information once you begin shopping.
- Keep financial records consistent and accessible.
Preparation can make it easier to respond to lender requests during underwriting.
Don’t Confuse Maximum Qualification With Comfortable Affordability
A mortgage lender’s maximum loan amount is based on its qualification criteria.
A household’s comfortable budget is a separate question.
For example, two households might qualify for the same mortgage amount but have very different financial priorities because of differences in:
- Childcare costs
- Education expenses
- Savings goals
- Transportation
- Medical expenses
- Lifestyle
- Retirement planning
- Other financial obligations
A responsible homebuying decision should therefore consider both lender qualification and the household’s broader financial plan.
The Mortgage Qualification Process in Perspective
Lenders qualify mortgage borrowers by examining the overall relationship between the borrower, the loan, and the property.
Income helps demonstrate repayment capacity. Employment information can provide context about income stability. Credit history provides information about past borrowing behavior. Existing debt affects monthly obligations, while assets and savings demonstrate available funds and financial reserves.
The property itself is also evaluated because it serves as collateral for the mortgage.
For buyers, understanding these factors can make the mortgage process less mysterious and make it easier to prepare before submitting an application.
Building a Stronger Mortgage Application
Mortgage qualification is ultimately a process of documenting financial capacity and evaluating whether a proposed loan fits the lender’s requirements.
Borrowers can prepare by understanding their income, debts, credit history, savings, and expected housing costs before beginning the application. They should also research the property carefully and account for expenses beyond the monthly mortgage payment.
The most useful distinction to remember is that being approved for a mortgage and being comfortable with the resulting financial commitment are two different questions. A well-prepared buyer considers both before moving forward with a home purchase.