New-Home Sales Slump Raises Fresh Questions for Home Improvement Demand
New-Home Sales Slump Raises Fresh Questions for Home Improvement Demand
The U.S. housing market is showing another sign of strain, and the slowdown could reach beyond homebuilders and real estate agents.
New-home sales fell sharply in July, with higher borrowing costs and affordability concerns continuing to keep potential buyers on the sidelines. The weakness raises an important question for the broader housing economy: what happens to home improvement demand when fewer people are buying newly built homes?
The answer is complicated. A slowdown in new-home purchases can reduce spending on immediate upgrades and move-in projects, but it can also create opportunities elsewhere in the home improvement market as homeowners choose to renovate rather than move.
New-Home Sales Fell Sharply in July
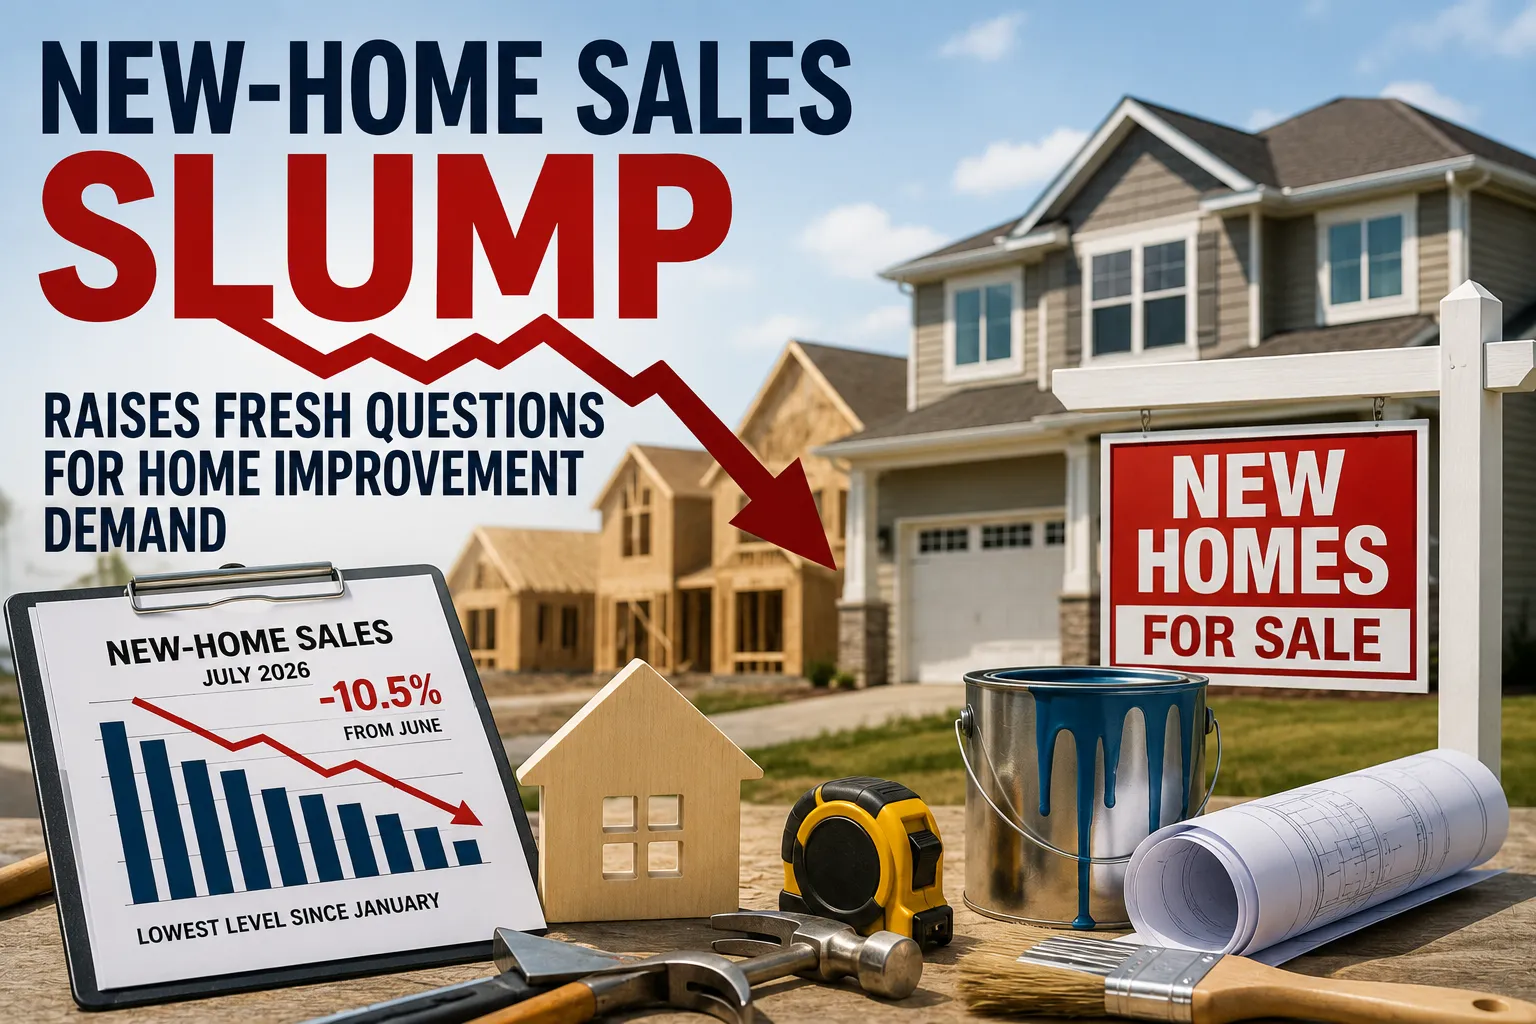
Sales of newly built single-family homes dropped to a seasonally adjusted annual rate of 607,000 in July, according to the latest U.S. Census Bureau and Department of Housing and Urban Development data.
That was a 10.5% decline from June’s 678,000 rate and a 6.3% decline from July 2025. The July pace was the lowest since January.
The decline came even as the market offered buyers somewhat more inventory.
There were an estimated 488,000 new homes for sale at the end of July, representing 9.6 months of supply at the prevailing sales pace. The median price of a new home fell to $393,800, down from $403,100 in June and slightly below the $397,300 recorded a year earlier.
That combination tells an important story: builders have more homes available, but buyers remain reluctant to commit.
High Mortgage Rates Continue to Weigh on Buyers
Mortgage costs remain one of the biggest obstacles facing prospective homeowners.
Mortgage rates had climbed to roughly 6.77% in mid-August, according to Reuters, after rising about 0.60 percentage points since late February. Higher monthly payments make it harder for households to qualify for homes or justify taking on a larger mortgage.
The Mortgage Bankers Association also reported that applications for mortgages to purchase newly built homes fell 5.7% year over year in July and 1% from June. The association said elevated inventory and buyer sensitivity to mortgage rates were weighing on demand.
For homeowners, the issue extends beyond the mortgage payment.
A buyer who stretches financially to purchase a home has less money available for painting, flooring, landscaping, furniture, appliances and remodeling.
That can directly affect the home improvement industry.
Why New Home Sales Matter for Home Improvement
New-home purchases often trigger a wave of spending.
Even when a newly constructed house is technically move-in ready, buyers may want to customize it.
They may spend on:
- Paint and wall treatments
- Lighting
- Window coverings
- Landscaping
- Furniture
- Appliances
- Storage systems
- Outdoor living spaces
- Flooring upgrades
- Smart-home technology
- Home offices
These purchases can occur shortly after closing, making new-home sales an important source of potential demand for retailers, contractors and manufacturers.
When fewer homes change hands, some of that spending can disappear or be postponed.
For homeowners who remain in their current properties, however, the broader Home Maintenance Projects category can continue generating demand even when housing transactions slow.
Builders Are Already Facing a Difficult Environment
The slowdown in sales is occurring alongside weaker construction activity.
U.S. housing starts fell 12.4% in July from June, while single-family housing starts dropped 9.9%. Single-family completions also declined.
For companies involved in residential construction and home improvement, that creates a challenging environment.
Builders have to manage inventory while deciding how aggressively to start new projects. Contractors can face less demand from newly constructed properties. Suppliers may see fewer orders for materials and fixtures.
At the same time, homeowners who are not moving still need to maintain and improve their existing properties.
That creates a crucial distinction between transaction-driven demand and homeownership-driven demand.
The Remodeling Market May Not Move in Lockstep With Home Sales
A weak housing market does not necessarily mean that all home improvement spending will collapse.
Homeowners still have leaking roofs, aging bathrooms, outdated kitchens and inefficient heating and cooling systems.
Some projects cannot easily be postponed.
Others may become more attractive when moving becomes less affordable.
A homeowner who cannot justify selling and purchasing another property might instead decide to renovate the house they already own.
This dynamic can provide some protection for the remodeling industry during a housing slowdown.
The distinction between urgent work and optional upgrades is also central to the Home Repairs Guide: Common Problems and Solutions, since maintenance needs can persist regardless of housing-market activity.
Staying Put Can Encourage Renovation
High mortgage rates have changed the economics of moving for many existing homeowners.
Someone who secured a relatively low mortgage rate several years ago may be reluctant to sell and take out a new loan at a substantially higher rate.
That can create a phenomenon sometimes described as mortgage-rate lock-in.
Instead of moving to a different home, households may choose to improve their current one.
A kitchen renovation, finished basement, additional bedroom, outdoor living area or home office can make an existing property better suited to changing needs.
In that sense, a weak housing market can simultaneously hurt some home improvement categories while supporting others.
Necessary Repairs Are Different From Discretionary Upgrades
Not all home improvement spending is equally sensitive to economic conditions.
A homeowner may postpone installing a new entertainment system or renovating a perfectly functional bathroom.
Replacing a failed water heater is different.
Fixing a leaking roof is different.
Repairing an electrical problem is different.
This distinction is important because the home improvement industry includes everything from emergency maintenance to luxury remodeling.
During periods of economic uncertainty, discretionary projects may be delayed while essential repairs continue.
Understanding the systems behind those repairs is also useful, particularly when homeowners need to determine whether a problem involves plumbing, electrical, HVAC or another major component. The guide to how major home systems work and what homeowners maintain provides broader context for those decisions.
Large Remodeling Projects Could Face More Pressure
Major renovations require substantial upfront spending.
A whole-house renovation, major kitchen remodel or large addition can involve tens of thousands of dollars or more.
When consumers are worried about employment, inflation, mortgage payments and household budgets, these projects can be easier to postpone.
That is particularly relevant when financing costs are high.
Even households that have enough home equity to fund a renovation may hesitate to borrow additional money when interest rates remain elevated.
Smaller Projects Could Hold Up Better
Smaller improvement projects may be more resilient.
Instead of remodeling an entire kitchen, a homeowner might replace cabinet hardware, repaint the walls or install new lighting.
Instead of rebuilding a backyard, they might add a small patio or improve landscaping.
These projects require less money and can often be completed in stages.
For consumers, breaking a large renovation into smaller projects can make spending more manageable.
For retailers and contractors, it can mean that demand does not disappear entirely even when major projects slow.
Homeowners Still Have Equity
Another factor supporting renovation demand is the amount of equity many existing homeowners have accumulated.
Years of home-price appreciation have left many owners with significant differences between the value of their properties and their outstanding mortgage balances.
That equity can provide financial flexibility for some households.
However, having equity does not mean a homeowner will automatically spend it.
Borrowing costs, income, job security and expectations about future home prices all influence renovation decisions.
The Remodeling Decision Is Becoming More Strategic
When housing costs are high, homeowners may increasingly evaluate renovations based on practical value.
A project that improves energy efficiency, addresses maintenance problems or adds useful living space may appear more attractive than a purely cosmetic upgrade.
For example, homeowners might prioritize:
- Replacing an inefficient HVAC system
- Improving insulation
- Installing energy-efficient windows
- Repairing roofs
- Updating electrical systems
- Improving water efficiency
- Creating flexible living spaces
These projects can provide immediate functional benefits while potentially improving the long-term usefulness of the property.
For households trying to decide which work deserves priority, How to Budget for Home Maintenance can help put recurring maintenance and larger replacement costs into a more structured financial plan.
Energy Efficiency Could Remain an Important Category
Energy-related upgrades occupy an interesting position in the current environment.
They require upfront investment, but they can potentially reduce household operating costs over time.
As consumers remain sensitive to utility bills and household expenses, projects designed to improve efficiency may receive more attention.
Heat pumps, insulation, efficient appliances, solar systems and smart thermostats are examples of upgrades homeowners may consider.
The economics vary significantly by location, energy prices, incentives and the condition of the existing home, so homeowners generally need to evaluate the expected payback rather than assuming every efficiency upgrade will save money.
That is particularly relevant as households weigh the tradeoffs described in Common Home Energy Efficiency Mistakes, where poorly planned efficiency improvements can undermine the expected benefits.
Home Improvement Retailers Are Watching the Housing Market
The relationship between housing activity and home improvement sales makes housing data an important indicator for retailers.
Fewer home purchases can mean fewer move-in projects.
But a larger population of homeowners staying put can create another type of demand.
That makes the composition of sales particularly important.
A retailer serving homeowners who are renovating existing properties may be less exposed to the new-home market than a business heavily dependent on builders and new construction.
Companies also have to distinguish between professional contractors and do-it-yourself consumers, since the two groups can respond differently to economic conditions.
Contractors May Face a Mixed Market
Contractors could see different effects depending on their specialty.
Businesses focused heavily on new construction may feel the slowdown quickly if builders reduce projects.
Remodeling contractors could see a different pattern.
Some homeowners may postpone renovations because of economic uncertainty, while others may decide that improving their current home makes more sense than moving.
Specialists in essential repairs may be relatively insulated from the broader slowdown.
This means there is no single “home improvement market” responding in exactly the same way.
The New-Home Market Could Create Opportunities for Buyers
The slowdown is not entirely negative for consumers.
More inventory and weaker demand can give buyers greater negotiating power.
The Census Bureau reported 9.6 months of supply of new homes at the July sales pace, up from 8.5 months in June.
Builders facing higher inventories may become more willing to offer incentives, adjust prices or include upgrades to attract buyers.
For someone who can afford the purchase, that could create an opportunity to acquire a newly built home with features that might otherwise require additional spending after closing.
However, buyers still need to account for mortgage costs and the total cost of ownership.
Lower Prices Do Not Solve the Affordability Problem by Themselves
The median new-home price falling to $393,800 might appear encouraging.
But affordability depends on much more than the purchase price.
Mortgage rates, household income, property taxes, insurance, maintenance and other costs all influence the amount a buyer can comfortably afford.
A modest decline in the price of a home can be overwhelmed by higher financing costs.
This helps explain why new-home demand remains weak despite builders offering somewhat lower prices.
Consumer Confidence Adds Another Warning Sign
Housing decisions are also influenced by expectations.
The Conference Board’s consumer confidence index fell to 89.4 in August, its lowest level in seven months, as consumers expressed growing concerns about future business and labor-market conditions.
When households become uncertain about their financial future, large purchases are often the first decisions to be reconsidered.
Buying a home is one of the largest financial commitments most consumers make.
A major renovation can also represent a substantial investment.
Both decisions can therefore be delayed when confidence weakens.
What This Means for Homeowners Planning Renovations
The current environment does not necessarily mean homeowners should abandon improvement plans.
Instead, it may be a good time to prioritize projects carefully.
Before beginning a renovation, homeowners can consider:
- Whether the project is necessary or optional
- How much it will cost in total
- Whether the project can be completed in stages
- How the work will be financed
- Whether the project addresses a major maintenance issue
- Whether it improves energy efficiency
- How long the homeowner expects to remain in the property
This approach can help separate improvements that genuinely solve a problem from projects driven primarily by short-term trends.
What Could Change the Outlook?
The trajectory for home improvement demand will depend partly on what happens to mortgage rates and household confidence.
If borrowing costs eventually fall, more buyers could return to the housing market.
That would potentially increase spending associated with home purchases and stimulate activity among builders, contractors, retailers and suppliers.
If rates remain elevated and economic uncertainty continues, households may stay in their current homes longer.
That could suppress transaction-driven spending while supporting certain remodeling and maintenance categories.
The direction of the housing market therefore matters, but it is not the only factor determining the outlook for home improvement.
A Housing Slowdown With Two Sides
The July new-home sales figures provide another reminder that the U.S. housing market remains under pressure.
New-home sales fell 10.5% in July to a 607,000 annual rate, while inventory rose and the median new-home price slipped below $400,000. At the same time, mortgage applications for new-home purchases were down from a year earlier.
For the home improvement industry, the implications are less straightforward than the headline numbers might suggest.
Fewer home purchases can reduce immediate spending on upgrades, furnishings and move-in projects. But homeowners who are unwilling or unable to move may instead invest in the properties they already own.
That could make repair, maintenance, energy efficiency and selective remodeling more important sources of demand as the housing market works through its affordability and financing challenges.
For consumers, the current environment may ultimately encourage a more deliberate approach to home improvement: spend where the work solves a real problem, improves the usefulness of the property or provides lasting value, rather than assuming that every upgrade needs to happen at once.